Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
The Money Side of Real Estate
The Money Side of Real Estate
Let’s say a home is listed for $600,000.
Instead of simply paying full price, the buyer negotiates:
Purchase Price: $580,000
Seller Credit: 3% = $17,400
Now the buyer has accomplished two different things.
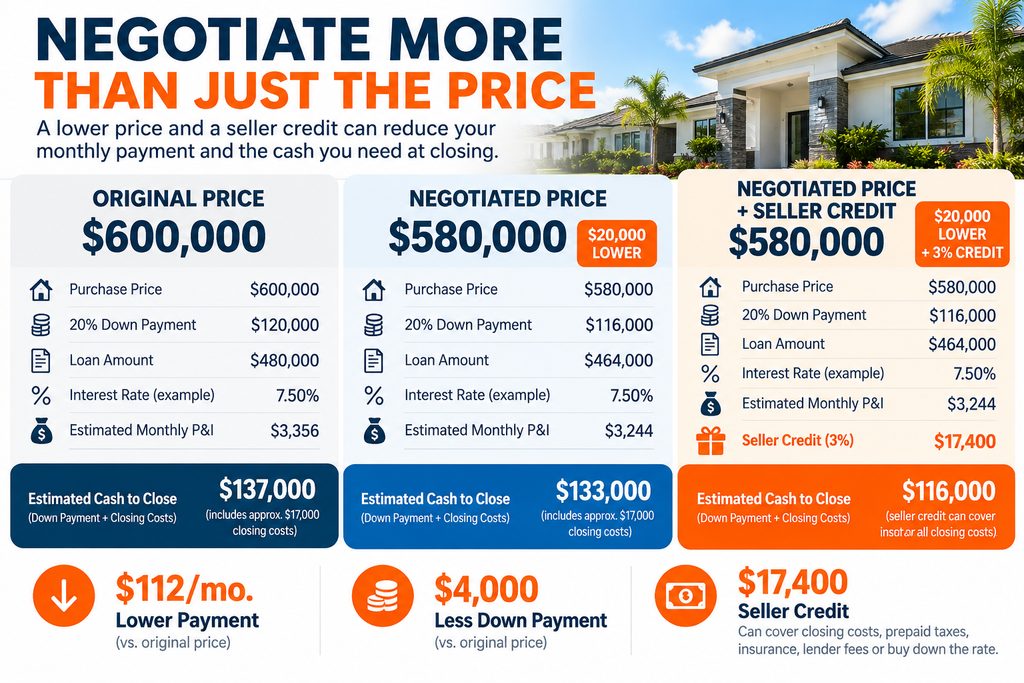
With 20% down, the loan drops from approximately $480,000 to $464,000.
At an example rate of 7.50%, the principal-and-interest payment drops from roughly:
$3,356 → $3,244
That’s about $112 per month in savings.
The buyer also needs about $4,000 less for the down payment.
This can be even more important.
A seller credit generally can’t be used for the buyer’s down payment, but depending on the loan program it may be used toward allowable:
So imagine the buyer has approximately $17,000 in eligible closing costs and prepaid expenses.
Instead of bringing that money to closing themselves, the negotiated seller credit could potentially cover most or all of it, subject to the loan program’s seller-contribution limits.
Without negotiating:
$600,000 purchase
$120,000 down
After negotiating:
$580,000 purchase
$116,000 down
That’s roughly $21,000 less cash out of the buyer’s pocket, while also lowering the mortgage payment.
And there may be another strategy.
Instead of using the entire seller credit toward closing costs, some buyers may use part of the credit to buy the mortgage rate down.
That could make the monthly-payment savings greater than simply reducing the sales price.
A buyer shouldn’t only ask:
“How much will the seller reduce the price?”
Ask:
“How can we structure the price, seller credit and financing to give me the best combination of monthly payment and cash needed at closing?”
On a $600,000 house, a $20,000 price reduction is helpful.
But a price reduction plus a seller credit can have a much bigger immediate impact.
Negotiate the house. Negotiate the closing costs. Negotiate the financing.
That’s the money side of real estate.